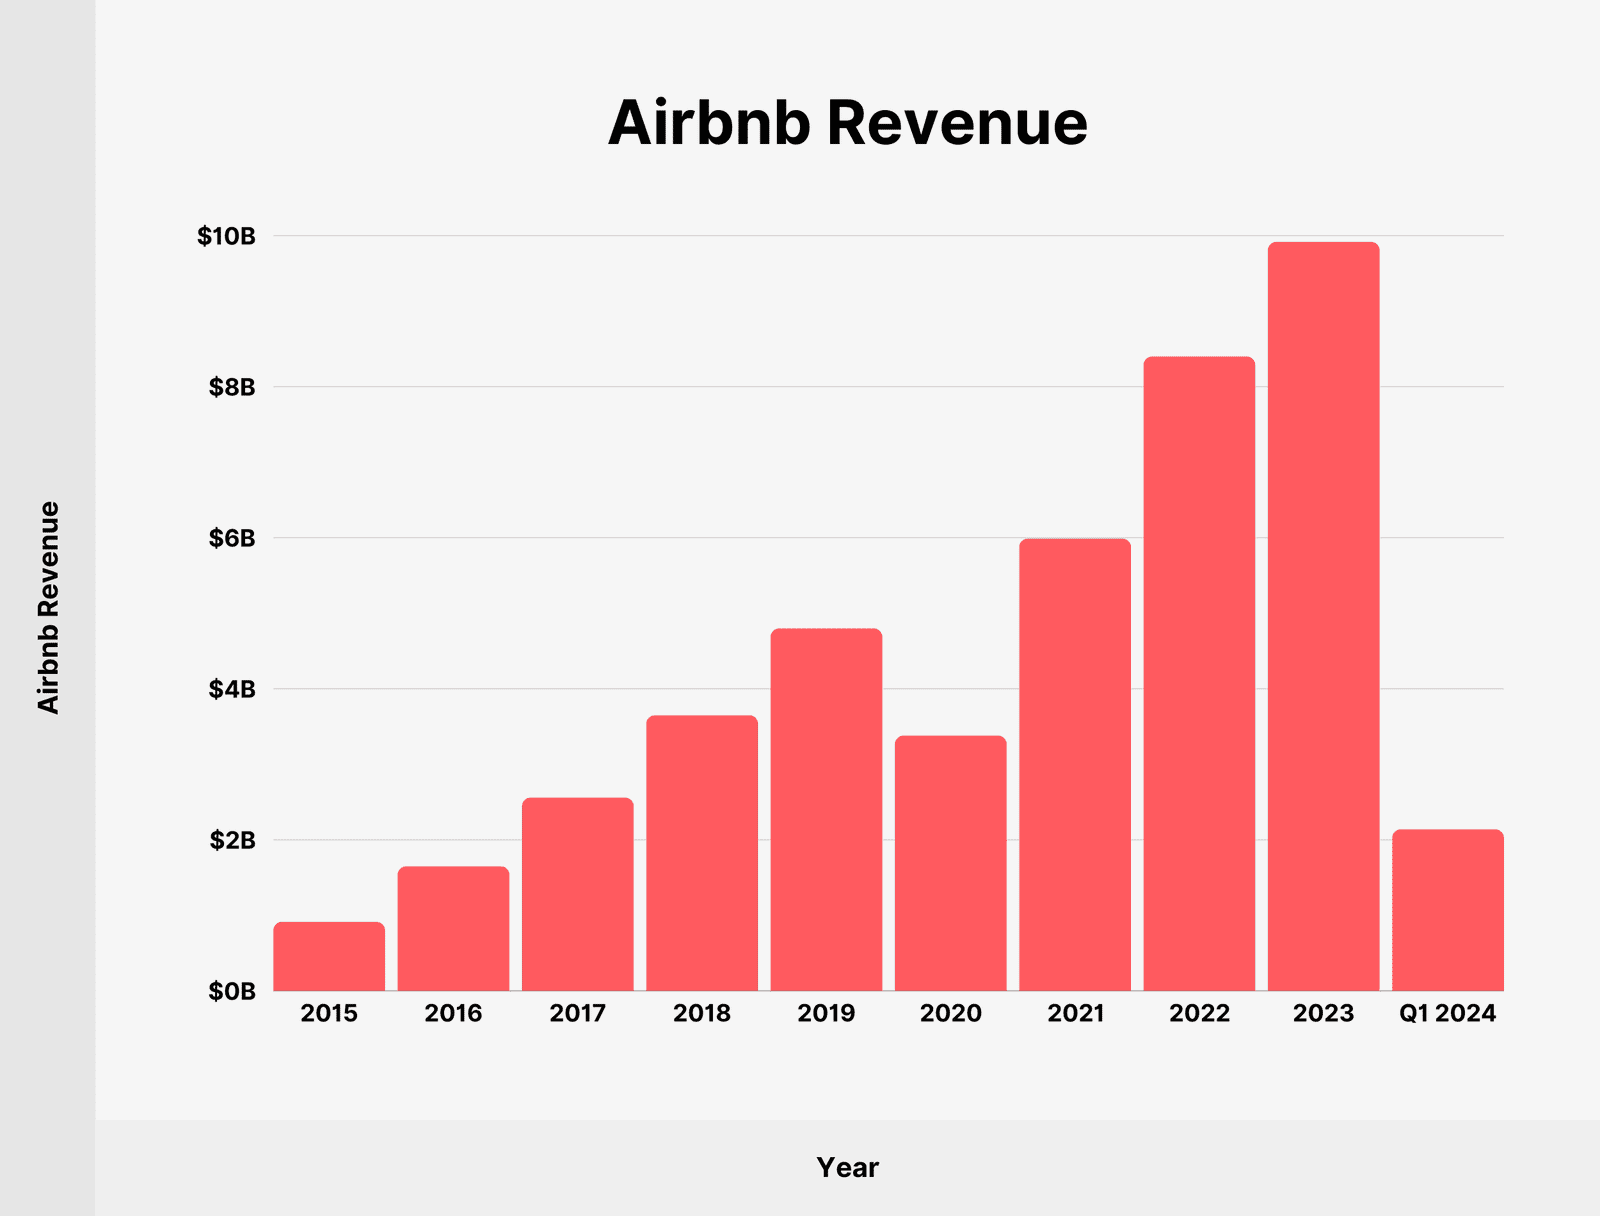
An income figure shows money coming in over time. A personal balance sheet shows what is owned and owed at a particular date. Keeping both views helps distinguish cash flow from accumulated financial position.
Start with assets minus liabilities
The CFPB’s financial toolkit defines net worth as the difference between assets and liabilities. Assets are items of value; liabilities are amounts owed. A useful worksheet records both on the same date.
A hypothetical household snapshot
Imagine $8,000 in cash, $22,000 in investments and a vehicle valued at $12,000. Total listed assets are $42,000. If a car loan balance is $7,000 and a credit card balance is $3,000, total liabilities are $10,000.
Net worth is therefore $32,000. That does not mean $32,000 is available in the checking account. Only $8,000 in this simplified example is listed as cash.
Keep liquidity separate
An asset may require a sale before money becomes available, and the amount realized may differ from the estimate. A household worksheet can therefore include separate columns for estimated value and accessibility.
For example, a vehicle used for commuting may appear in net worth without being a practical source for next week’s rent. Including it in the calculation does not solve a near-term cash shortage.
Avoid double-counting debt
If the vehicle is listed at its full estimated value, show the associated loan among liabilities. Do not list only the vehicle’s equity and then subtract the same loan again. Either consistent approach needs clear labels.
Use current debt balances rather than original borrowing amounts. For shared assets and obligations, document the ownership approach used so that comparisons remain consistent.
Review changes, not just the total
- Choose a repeatable review date.
- Update account balances and reasonable asset estimates.
- Separate debt repayments from asset-price movements.
- Keep cash needs alongside, rather than inside, the net-worth headline.
A rising estimate may reflect market prices rather than additional saving; a falling estimate may reflect a planned purchase or repayment pattern. The worksheet becomes useful when the cause of the change is visible. Net worth is a snapshot, while a budget explains the flows between snapshots.
Source
CFPB: Your Money, Your Goals—Personal Balance Sheet Guidance.
Featured image: Photo by Konstantin Evdokimov on Unsplash.