A savings account advertisement may display both an interest rate and an annual percentage yield, or APY. The figures can differ because APY reflects how earnings accumulate under the account’s stated assumptions. Understanding the distinction helps make a comparison more precise.
What APY describes
The CFPB’s APY calculation rules express yield on an annualized basis using interest earned relative to principal. The calculation generally assumes principal and interest remain on deposit for the relevant term, subject to specific account rules.
The stated interest rate and the frequency of compounding are therefore related to, but not always identical with, the annual yield displayed to a saver.
A hypothetical compounding example
Imagine a $10,000 deposit with a 4% nominal annual interest rate compounded monthly for a year. Under those assumptions, the balance becomes $10,000 × (1 + 0.04 ÷ 12) raised to the twelfth power, or about $10,407.42.
The effective annual increase is approximately 4.074%. This is a mathematical illustration, not a current bank offer. Actual account calculations follow their disclosures, including day-count and crediting conventions.
Fees can change the comparison
Now compare two hypothetical accounts with the same constant $10,000 starting balance. An account paying 4.2% APY produces $420 before fees over one year under a simplified unchanged-balance assumption. An account paying 4.0% produces $400.
If the first account separately charges $5 a month, its $60 annual fee exceeds the $20 interest advantage. This rough comparison treats fees separately and does not model their effect on daily balances.
Read the account disclosures
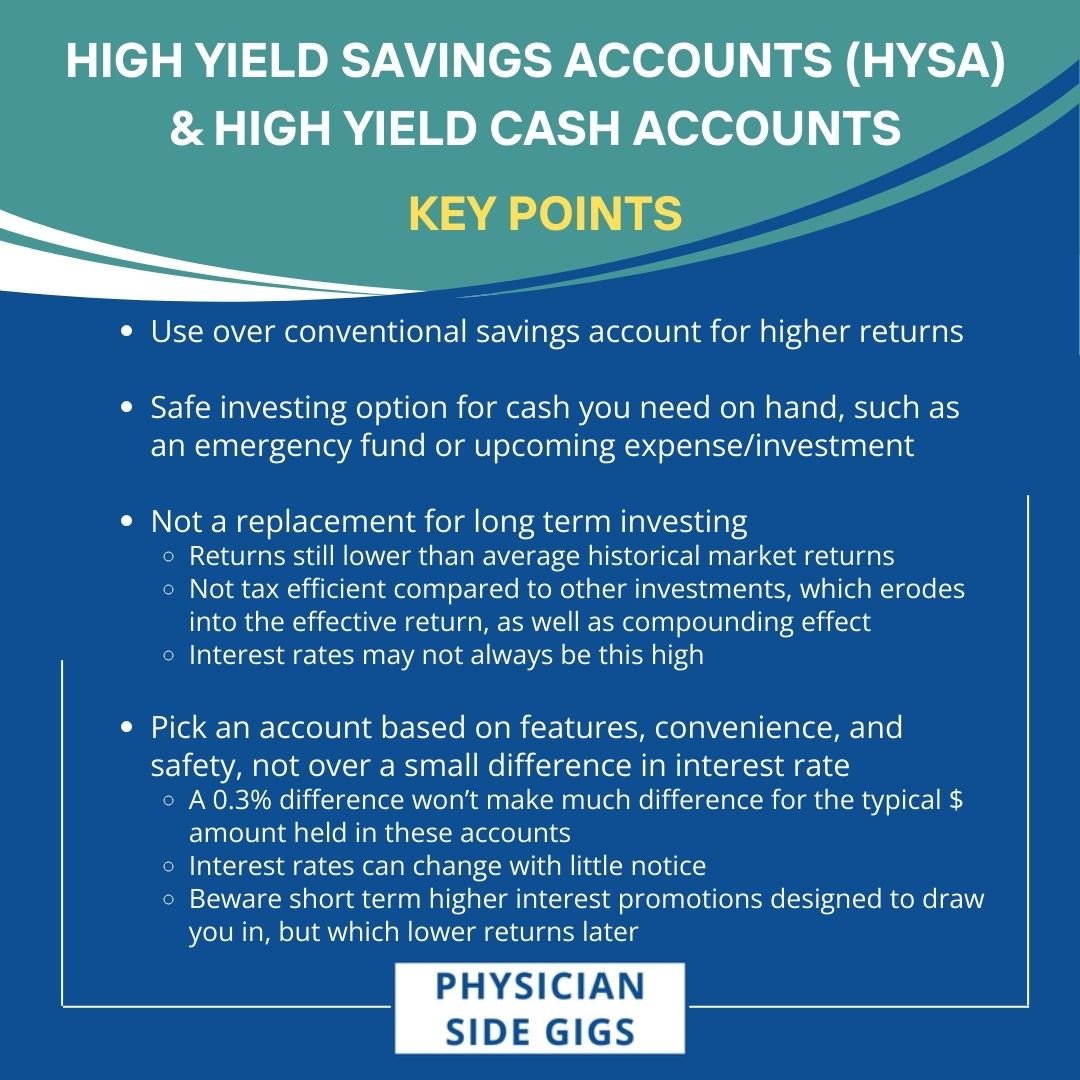
CFPB disclosure rules cover details including rate information, compounding and crediting, minimum balances and fees. For variable-rate accounts, the disclosures address the possibility of rate changes. A quoted APY should not be assumed to remain unchanged indefinitely.
A practical comparison checklist
- Record the APY and the date it was quoted.
- Check whether the rate is variable or promotional.
- Identify the balance needed to obtain the quoted yield.
- List monthly fees and the conditions for avoiding them.
- Check access, transfer timing and withdrawal conditions.
The useful comparison is the amount the account could leave you with under realistic conditions, alongside its access rules. A small difference in a headline percentage should be considered together with the rest of the account terms.
Sources
Featured image: Madison Kaminski / Unsplash.